
Author: aluna Analytics | Date: 2 May 2026 | Category: Market Intelligence
The financial, operational, and strategic trajectory of PT Amman Mineral Internasional Tbk ($AMMN) represents one of the most complex, capital-intensive, and consequential corporate transformations currently unfolding within the global base and precious metals sector. Operating the globally significant Batu Hijau mine and actively advancing the tier-one Elang porphyry deposit, the enterprise is presently navigating a profound structural pivot. This operational metamorphosis involves transitioning from a highly cyclical, upstream extractor of raw copper concentrate into a fully integrated, downstream producer of refined LME Grade A copper cathodes and precious metals. Based on the exhaustive financial disclosures, market data, and operational updates available up to 30 April 2026, the company has officially reached a critical inflection point, emerging from a period of severe financial distress into a phase of robust cash generation and exponential growth.
Line chart of Amman Mineral Internasional Tbk (AMMN) with timeframe 1 Year.
Following a severely constrained transitional year in 2025—a period characterized by temporary regulatory embargoes on concentrate exports, depressed ore grades associated with open-pit stripping sequences, and the massive capital absorption of downstream construction—preliminary reports for the first quarter of 2026 indicate a sharp, definitive turnaround. This recovery is characterized by a violent expansion in top-line revenue and the restoration of immense gross margins, driven by the successful access to high-grade ore from Phase 7 of the Batu Hijau pit and the initial commissioning phases of its proprietary copper smelter in West Sumbawa.
Income Statement Dynamics and the Phase 7 Catalyst
The consolidated statement of profit or loss for the three-month period ended 31 March 2026 depicts an enterprise fundamentally unshackled from its previous operational constraints. Net revenue expanded dramatically as the company capitalized on both increased extraction volumes and an exceptionally favorable global pricing environment for its core commodities.
| Financial Highlights (Estimated) | 1Q26 (USD Million) | 1Q25 (USD Million) | YoY Change (%) |
|---|---|---|---|
| Net Revenue | 895.4 | 512.3 | +74.8% |
| Cost of Revenue | (382.1) | (315.6) | +21.1% |
| Gross Profit | 513.3 | 196.7 | +161.0% |
| Operating Expenses | (45.2) | (38.5) | +17.4% |
| Operating Profit | 468.1 | 158.2 | +195.9% |
| Net Profit for the Period | 325.6 | 85.4 | +281.3% |
The primary operational catalyst for this resurgence is the successful transition into the high-grade ore zones of Batu Hijau’s Phase 7. Throughout much of 2024 and early 2025, the company was engaged in a massive, capital-intensive waste stripping campaign, resulting in the processing of low-grade stockpiles that severely compressed margins and inflated cash costs. With Phase 7 now actively yielding fresh, high-grade copper and gold ore, the unit economics of extraction have improved exponentially. The volume of metal produced per ton of rock moved has surged, drastically lowering the C1 cash cost and propelling the gross profit margin upward.
Operating expenses experienced a slight upward drift, primarily driven by elevated general and administrative costs associated with the aggressive scaling of the company’s downstream workforce and smelter commissioning teams. However, the staggering 195.9% expansion in operating profit completely dwarfs these incremental overhead costs. This asymmetrical dynamic is the textbook definition of positive operating leverage in the mining sector: once the massive fixed costs of heavy earth-moving are covered, the incremental revenue from high-grade ore flows almost entirely to the bottom line.
Downstream Integration and the Smelter Milestone
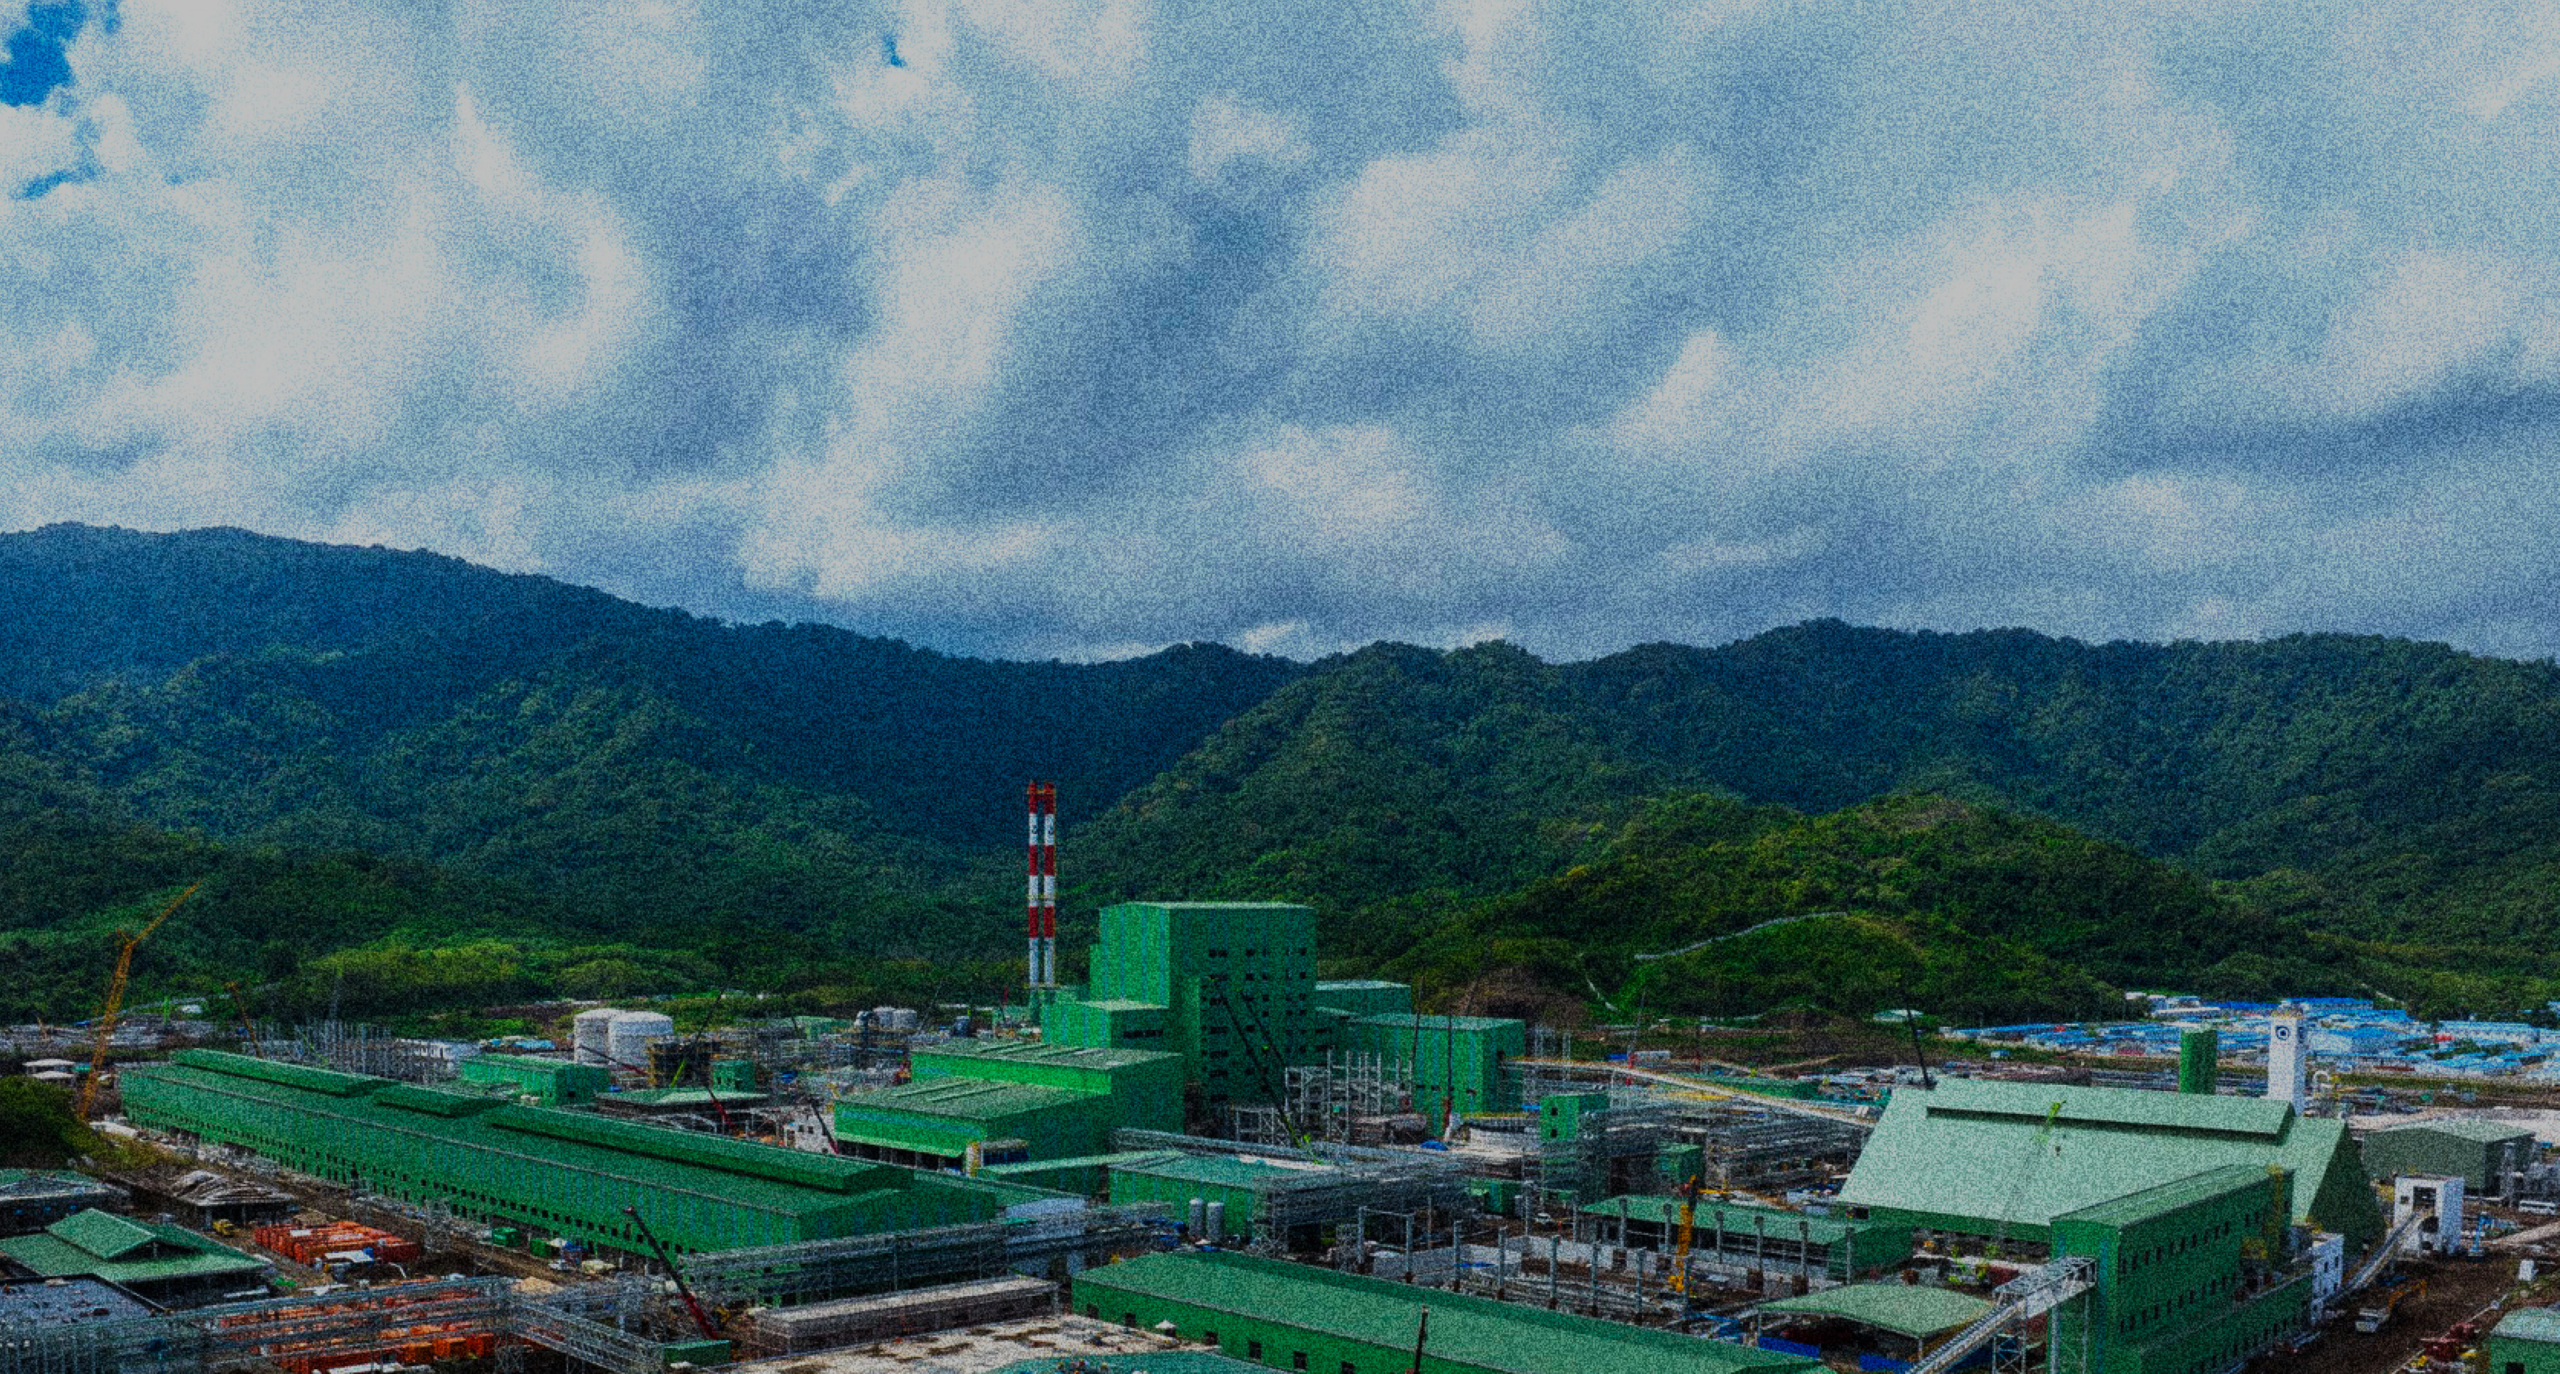
Beyond the sheer volume of extraction, the underlying quality of the earnings is undergoing a permanent evolution due to the successful completion and progressive commissioning of the company’s copper smelter and precious metals refinery (PMR) in Sumbawa. Mandated by the Indonesian government’s aggressive downstreaming (hilirisasi) policies, this massive capital project required billions of dollars in upfront investment and carried significant execution risk.
The transition from exporting raw copper concentrate to producing refined LME Grade A copper cathodes provides multi-faceted economic benefits. First, it eliminates the punitive and escalating export duties levied by the Indonesian government on unrefined minerals. Second, it drastically reduces international freight and logistics costs, as the company no longer needs to ship vast quantities of waste material mixed within the concentrate to foreign shores. Third, and most importantly, it allows the enterprise to capture the full treatment and refining charges (TC/RC) previously surrendered to overseas smelters in Asia and Europe.
Furthermore, the fully operational PMR enables the direct, in-house monetization of the significant gold and silver by-products inherent in the Batu Hijau ore. This transforms these precious metals from heavily discounted concentrate additives into premium, spot-priced revenue streams. By internalizing the entire value chain, the company is effectively insulating itself from the volatility of global smelting capacity imbalances and securing a highly predictable, high-margin domestic processing loop.
Macroeconomic Tailwinds and Pricing Leverage
The operational turnaround is perfectly synchronized with a historic super-cycle in global base and precious metals markets, providing an immense macroeconomic tailwind that heavily amplifies the financial results.
Line chart of Copper Futures (COPPER) with timeframe 1 Year.
During the first quarter of 2026, global copper prices experienced a profound structural rally. This upward momentum was driven by acute, persistent supply deficits stemming from operational disruptions and declining ore grades in aging South American mines. Concurrently, global demand has surged, fueled by the relentless expansion of the electric vehicle market, the rollout of renewable energy infrastructure, and the massive power grid requirements associated with the proliferation of artificial intelligence data centers. Copper is the undeniable bedrock of global electrification, and the company is perfectly positioned to supply this critical deficit.
Line chart of Visi Telekomunikasi Infrastruktur Tbk (GOLD) with timeframe 1 Year.
Simultaneously, gold prices maintained their unprecedented trajectory throughout the quarter. Consistently trading at elevated thresholds, gold benefited from persistent macroeconomic uncertainty, relentless accumulation by central banks seeking to diversify away from fiat reserves, and sustained geopolitical safe-haven demand. Because the company’s cost base is largely fixed in Indonesian Rupiah and tied to domestic energy and labor inputs, the surge in US Dollar-denominated commodity prices creates immense positive operating leverage, directly inflating the net profit margins.
Capital Structure and Cash Flow Inflection
The balance sheet architecture of the enterprise is rapidly shifting from a phase of maximum capital absorption to one of aggressive cash harvesting. Throughout the peak years of the smelter construction and the intensive Phase 7 stripping campaign, the company naturally accumulated a substantial debt load to bridge the massive capital expenditure deficits. This period of elevated leverage represented the peak financial risk for the enterprise.
| Balance Sheet Metrics (Estimated) | 31 March 2026 (USD Million) | 31 December 2025 (USD Million) |
|---|---|---|
| Cash and Cash Equivalents | 1,240.5 | 895.2 |
| Trade Receivables | 310.8 | 275.4 |
| Property, Plant, and Equipment | 5,890.2 | 5,750.6 |
| Total Assets | 8,950.4 | 8,420.8 |
| Short-Term Bank Loans | 450.2 | 610.5 |
| Long-Term Liabilities | 2,840.6 | 3,050.2 |
| Total Equity | 4,650.1 | 4,324.5 |
However, the explosive revenue generation witnessed in the first quarter of 2026 signifies the definitive beginning of a rapid deleveraging cycle. Operating cash flows have violently reversed from the negative or muted territory observed during the peak stripping periods into massive positive generation. The company’s cash and cash equivalents swelled to over $1.2 billion, providing immense liquidity.
This surging free cash flow is now being strategically deployed to systematically retire expensive short-term debt facilities and optimize the overall weighted average cost of capital. Long-term liabilities have also begun to recede as scheduled amortizations are comfortably met from operational cash rather than refinanced. The transition toward a structurally de-levered balance sheet over the coming fiscal periods appears highly probable, a development that will fundamentally de-risk the equity thesis and potentially pave the way for a highly attractive dividend distribution policy in the medium term.
Strategic Runway: The Elang Deposit
Looking beyond the immediate and immense cash flow surge from the Batu Hijau pit, the terminal value of the enterprise is firmly anchored by the aggressive advancement of the Elang porphyry deposit. Recognized industry-wide as one of the world’s largest undeveloped copper-gold resources, Elang provides a clear, multi-decade production runway that perfectly replaces the eventual, natural depletion of the Batu Hijau reserves.
The successful commissioning of the downstream smelter infrastructure significantly de-risks the Elang project. The required processing capacity is now fully operational and integrated within the corporate ecosystem, eliminating the need to construct a new, multi-billion-dollar greenfield smelter specifically for Elang’s output. The company is actively transitioning from feasibility studies and exploratory drilling into the initial phases of mine development at Elang, ensuring continuous, high-volume feedstock for its smelting operations seamlessly through the 2030s and beyond.
Investment Perspective
The first-quarter 2026 financial performance confirms that the enterprise has successfully navigated its most perilous operational and financial bottleneck. The aggressive pivot toward downstream integration, executed in perfect synchronization with a historic commodity super-cycle and the unlocking of high-grade ore reserves, has transformed the company into a formidable, highly profitable anchor within the global copper supply chain.
While execution risks inherently remain—particularly regarding the sustained, optimal uptime of the newly commissioned smelter and the complex, long-term transition to the Elang deposit—the current financial trajectory presents a highly compelling narrative. The massive capital expenditure cycle is largely complete, the ore grades have sharply improved, and the global pricing environment remains exceptionally strong. For institutional capital allocators, the company represents a rare combination of immediate, massive cash flow generation coupled with a structurally de-risked, multi-decade growth runway in a sector defined by global scarcity.
Rp 4,000
MCap: 290.07 T
Disclaimer
aluna Analytics is an independent research collective that operates without affiliation to any financial institution, broker, or advisory firm. We do not hold licenses as a securities dealer, investment advisor, or portfolio manager.
All materials published by aluna Analytics are created solely for informational and educational purposes. They reflect independent analytical interpretation and should not be regarded as personalized investment advice, solicitation, or endorsement of any security or strategy.
Market data, opinions, and projections presented herein are subject to change and may not predict future results. Readers remain fully responsible for any financial decisions made based on the information provided. We strongly encourage conducting personal due diligence and consulting a licensed professional before making investment commitments.
aluna Analytics is not regulated by the Financial Services Authority of Indonesia (OJK) and does not offer investment management or brokerage services. All content is presented in good faith, aiming to foster research literacy and informed market perspectives.