
Author: aluna Analytics | Date: 29 April 2026 | Category: Market Intelligence
The first quarter of 2026 presented a highly complex macroeconomic environment characterized by volatile commodity markets, shifting geopolitical fault lines, and subdued domestic property development. Despite these profound external pressures, PT Avia Avian Tbk ($AVIA) and its subsidiaries delivered a remarkably robust financial performance for the three-month period ended March 31, 2026.
The company demonstrated significant top-line expansion, with net revenues surging by 16.8% year-over-year, driven by aggressive market penetration and double-digit growth across both its core architectural solutions and trading goods segments. This was achieved while maintaining high-quality cash conversion metrics, evidencing a structural advantage in working capital management and proprietary distribution. However, underlying pressures remain apparent. The escalation of global crude oil prices, exacerbated by the Iran conflict and disruptions in the Strait of Hormuz, has initiated a cycle of raw material inflation that subtly compressed gross margins during the quarter.
A deep dive into the balance sheet highlights an exceptionally conservative capital structure. The company holds zero long-term interest-bearing bank debt and commands a massive liquidity pool, representing an overcapitalized balance sheet. While this fortifies the company against systemic shocks, it also raises questions regarding capital allocation efficiency and the opportunity cost of idle capital. Dependency risks, particularly the heavy reliance on related-party suppliers for raw materials, present structural vulnerabilities that require careful monitoring. Ultimately, the company exhibits the financial architecture of a high-quality compounder, possessing a wide economic moat, dominant market share, and formidable pricing power, which collectively justify a premium valuation framework in the public equity markets.
Line chart of Avia Avian Tbk (AVIA) with timeframe 1 Year.
Disclaimer: This analysis is strictly limited to data available up to 29 April 2026. This content is for informational purposes only and does not constitute financial advice, an offer to sell, or a solicitation of an offer to buy any securities. All investments involve risk, including the loss of principal.
Business Profile and Economic Fundamentals
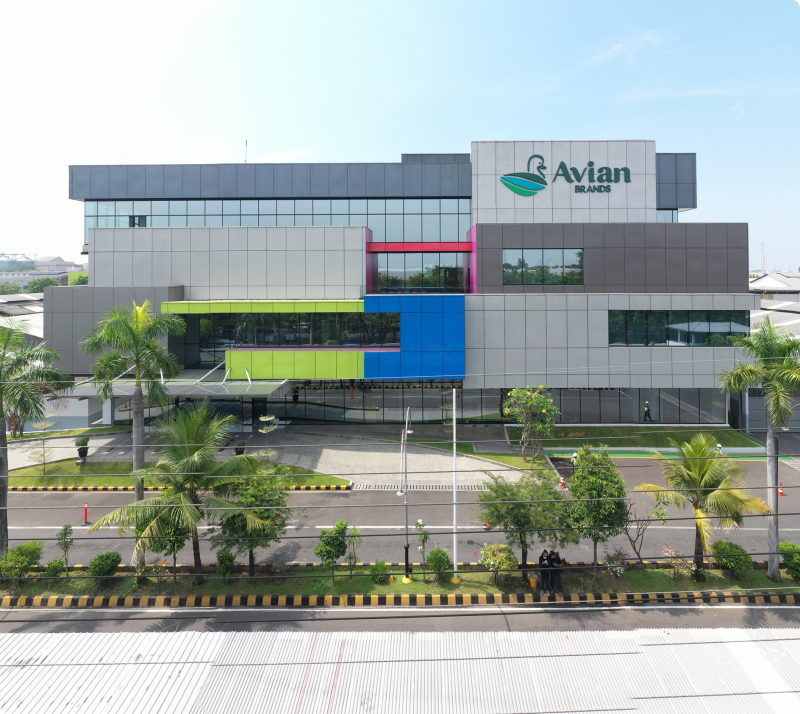
PT Avia Avian Tbk operates as the undisputed market leader in the Indonesian decorative paint and coatings industry. The fundamental mechanics of the business revolve around the manufacturing, distribution, and sale of architectural paints, waterproofing solutions, wood and metal coatings, and related building materials. The business model is deeply vertically integrated, extending from the internal manufacturing of specific raw materials to a vast, proprietary distribution network that blankets the Indonesian archipelago.
The company segments its operations into two primary divisions: Architectural Solutions and Trading Goods. The Architectural Solutions segment is the core economic engine of the enterprise, historically contributing approximately 80% of total revenue. This segment encompasses the production of proprietary branded paints and coatings formulated in the company’s advanced manufacturing facilities. In recent years, the company has heavily invested in research and development, establishing the Avian Innovation Center in 2020, a 5,000-square-meter facility dedicated to product formulation and sustainability. The Trading Goods segment, contributing the remaining 20% of sales, involves the distribution of complementary building materials, notably PVC pipes and related hardware. This segment allows the company to leverage its existing logistics infrastructure to capture a larger share of the retail building materials market without requiring substantial additional capital expenditure.
The economic strength of the company is structurally rooted in its distribution architecture. Unlike consumer packaged goods companies that rely heavily on third-party modern trade logistics, the enterprise utilizes a highly controlled distribution network. The financial data indicates that sales through the company’s own distributors overwhelmingly dominate its revenue mix, accounting for Rp 2.15 trillion of the Rp 2.36 trillion in total sales during the first quarter of 2026. Third-party distributors and direct sales make up a much smaller fraction of the revenue base. This proprietary network creates a formidable barrier to entry. Competitors attempting to capture market share must not only manufacture a competitive product but also replicate a nationwide logistics apparatus capable of servicing thousands of fragmented traditional retail hardware stores across Indonesia’s complex island geography.
This structural advantage allows the company to exert significant pricing power and maintain tight control over its brand positioning, inventory placement, and retail shelf space. The economics of the business are inherently highly cash-generative. Paint manufacturing is a relatively asset-light process once the initial mixing and blending infrastructure is established, requiring low maintenance capital expenditure to sustain current operations. The company’s ability to vertically integrate the production of key inputs, such as resins, further insulates it from upstream supply shocks and allows it to capture a larger percentage of the value chain. Consequently, the fundamental business profile is characterized by high return on invested capital, durable competitive advantages, and the capacity for sustained, profitable scaling.
Macroeconomic Paradigm and Industry Linkages
The financial performance cannot be viewed in isolation; it is deeply intertwined with the macroeconomic fabric of Indonesia and the volatile dynamics of global commodity markets. Understanding these external forces is critical to contextualizing the first-quarter achievements and forecasting the future trajectory.
| Macroeconomic Indicator | 2024 Actual | 2025 Actual | 2026 Forecast | 2027 Forecast |
|---|---|---|---|---|
| GDP Growth (%) | 5.0 | 5.1 | 5.2 | 5.2 |
| Inflation (%) | 2.3 | 1.9 | 2.5 | 2.5 |
The Indonesian economy has displayed robust resilience in the early months of 2026. Gross domestic product growth is projected to strengthen to 5.2% in 2026 and 2027, driven by a combination of cyclical momentum and policy-driven factors. Improved agricultural productivity has contributed to resilient rural income, while continued priority spending under the 2026 national budget has sustained household purchasing power and investment momentum. Furthermore, the stable price environment, with inflation forecast to remain within Bank Indonesia’s target range at 2.5%, provides the central bank with the flexibility to balance growth and stability.
However, the specific dynamics of the Indonesian real estate market present a more nuanced picture. In the first quarter of 2026, the broad residential property market remained subdued, marked by limited price appreciation, soft overall demand, and weak residential construction activity. While commercial and industrial real estate sectors, particularly warehousing and data centers in Greater Jakarta, exhibited strong demand and tight vacancies, the residential sector faced distinct headwinds. Data from the third quarter of the previous year indicated that sales of medium and large houses contracted severely by 12.27% and 23% year-over-year, respectively. Conversely, small residential property sales grew by 11.6%, highlighting a shift in consumer preference toward more affordable housing units.
The critical insight derived from correlating this macroeconomic data with the corporate financials is the decoupling of revenue growth from new large-scale residential construction. While new high-end property starts are stalling, the company continues to post near 17% revenue growth. This divergence proves that the architectural solutions segment is heavily insulated by the secondary renovation, repainting, and retail hardware markets. The business is fundamentally a consumer retail operation driven by home maintenance lifecycles and the resilient demand for small-ticket home improvements, rather than a cyclical construction materials play dependent on volatile developer pipelines.
Line chart of Brent Crude Oil Futures (OIL-BRENT) with timeframe 1 Year.
A more pressing external variable impacting the economics of the business is the global energy market. The escalation of military conflicts in the Middle East, specifically the tensions involving Iran and subsequent disruptions to maritime logistics in the Strait of Hormuz, has severely impacted global supply chains. The Strait of Hormuz is a critical choke point for global oil and liquefied natural gas flows, and the geopolitical instability caused crude oil prices to spike dramatically by 45% to approximately $95 per barrel in early 2026.
Because paint and coatings are heavily reliant on petrochemical derivatives, such as alkyd resins, titanium dioxide, and various hydrocarbon solvents, this crude oil volatility translates directly into raw material inflation. Smaller paint manufacturers in emerging markets, including India and Southeast Asia, are currently facing existential margin compression and production slowdowns due to these input costs. Global industry titans have explicitly warned investors of high teens percentage increases in their raw material baskets and have been forced to implement high-single-digit price increases globally to mitigate the damage. In addition to raw materials, higher fuel prices are raising transportation and logistics costs, further compounding the financial burden on producers. Furthermore, the depreciation of the Indonesian Rupiah against the US Dollar exacerbates the cost of imported raw materials. These macro-level supply chain bottlenecks form the essential backdrop for analyzing the cost of goods sold and gross margin trajectory in the first quarter.
Income Statement Dynamics and Earnings Quality
A granular examination of the consolidated statement of profit or loss reveals the operational momentum and profitability trajectory of the enterprise. The core income statement metrics for the three months ended March 31, 2026, compared to the corresponding period in 2025, highlight these dynamics.
| Income Statement Line Item | Q1 2026 (IDR Millions) | Q1 2025 (IDR Millions) | YoY Change (%) |
|---|---|---|---|
| Net Revenues | 2,357,880 | 2,018,597 | +16.8% |
| Cost of Goods Sold | (1,298,068) | (1,093,538) | +18.7% |
| Gross Profit | 1,059,812 | 925,059 | +14.6% |
| Selling Expenses | (391,694) | (339,105) | +15.5% |
| General & Administrative | (72,136) | (61,120) | +18.0% |
| Operating Profit | 595,982 | 524,834 | +13.5% |
| Finance Income | 49,936 | 66,323 | -24.7% |
| Finance Charges | (501) | (633) | -20.8% |
| Profit Before Tax | 653,646 | 579,840 | +12.7% |
| Income Tax Expense | (150,862) | (133,260) | +13.2% |
| Net Profit for the Period | 502,784 | 446,580 | +12.6% |
The company reported net revenues of Rp 2.35 trillion in the first quarter of 2026, representing a formidable 16.8% expansion over the Rp 2.01 trillion reported in the first quarter of 2025. This growth trajectory is exceptionally strong and was broad-based across both operating segments. Revenue recognition policies dictate that sales are recognized when control of the asset is transferred to the customer, generally upon the delivery of goods. The sales mix is heavily concentrated on independent third parties, which generated Rp 2.34 trillion in revenue, compared to a mere Rp 14.5 billion generated from related parties. This demonstrates that the top-line expansion is driven by genuine, external market demand rather than intra-group financial engineering.
While revenue growth was stellar, an analysis of the Cost of Goods Sold reveals underlying cost pressures. The cost of goods sold increased by 18.7% year-over-year to Rp 1.29 trillion, outpacing the 16.8% revenue growth. Consequently, the gross profit margin experienced a slight contraction, moving from 45.8% in the first quarter of 2025 down to 44.9% in the first quarter of 2026. This margin compression is a direct manifestation of the external macroeconomic shocks transmitting into the supply chain. A detailed breakdown of the production costs confirms this narrative. Raw material usage accounted for Rp 544.6 billion, while purchases of finished goods for resale amounted to Rp 448.9 billion. Factory overhead, including indirect labor, depreciation, and utilities, contributed Rp 35.4 billion, Rp 7.5 billion, and Rp 4.9 billion respectively to the total production cost of Rp 619.9 billion.
Despite these intense inflationary pressures on petrochemical derivatives, the ability to maintain a gross margin near 45% is a testament to formidable pricing power, vertical integration, and cost discipline. Proactive measures, which likely included targeted price hikes and strategic inventory accumulation, have effectively shielded the enterprise from the severe margin degradation experienced by smaller industry peers.
Operating expenses, comprising selling expenses and general and administrative expenses, totaled Rp 463.8 billion in the first quarter of 2026, up from Rp 400.2 billion in the prior year. Selling expenses, which represent the largest component of operational overhead, grew by 15.5% to Rp 391.6 billion. This growth is closely aligned with the volume expansion of the business. Employee salaries and benefits within the selling division grew to Rp 151.3 billion, indicative of an expanding sales force necessary to drive deeper market penetration. Freight out costs increased substantially from Rp 63.8 billion to Rp 82.2 billion, reflecting both higher sales volumes and increased logistics costs tied to the rise in global energy and fuel prices.
Furthermore, marketing and promotional expenses climbed to Rp 50.5 billion. The company employs complex accrual accounting for its marketing expenses, which are heavily tied to customer loyalty programs and volume rebates. The liability for these programs is measured using expected value methods under the Indonesian Financial Accounting Standard (PSAK) 115, ensuring that revenue is accurately constrained and variable consideration is properly accounted for. General and administrative expenses rose by 18.0% to Rp 72.1 billion, driven primarily by increases in salaries, depreciation, and professional fees. Despite the increases in both selling and administrative categories, the operating profit margin remained highly lucrative at 25.2%, demonstrating the scalability of the distribution network where incremental volumes generate high marginal returns.
Net profit for the period attributable to the owners of the parent company stood at Rp 503.1 billion, translating to an earnings per share of Rp 8.50, up from Rp 7.38 in the first quarter of 2025. The quality of these earnings is exceptionally high. The effective tax rate is approximately 23.0%, calculated from an income tax expense of Rp 150.8 billion on a profit before tax of Rp 653.6 billion. The tax calculation involves standard reconciliations for permanent differences, such as non-deductible expenses and income subject to final tax, as well as temporary differences related to depreciation, leases, and employee benefits. The financial statements report deferred tax assets of Rp 85.2 billion, primarily arising from accrued expenses and fixed asset depreciation timing differences, signaling conservative accounting practices where provisions are recognized well before they are realized for tax purposes. There is no evidence of aggressive accounting, capitalization of standard expenses, or artificial earnings inflation. The reported net income is a true reflection of the underlying economic reality of the enterprise.
Segment Performance and Competitive Positioning
Management determines operating segments based on internal reports reviewed by the Board of Directors, allocating resources and assessing performance according to product categories. The business is bifurcated into the Architectural Solutions segment and the Trading Goods segment.
| Segment | Revenue Q1 2026 | YoY Growth | Strategic Role |
|---|---|---|---|
| Architectural Solutions | ~80% of Total | +15.7% | Core manufacturing, high margin, proprietary brands |
| Trading Goods | ~20% of Total | +21.6% | Distribution leverage, complementary products (PVC) |
The Architectural Solutions segment serves as the primary engine for profitability. During the first quarter of 2026, this segment recorded a growth rate of 15.7%, supported by a robust 12.6% increase in underlying sales volume. This volume growth is a critical indicator of business quality; it confirms that the top-line expansion was not merely an inflationary price illusion but was supported by tangible increases in product movement and market share capture. The Trading Goods segment outperformed on a relative basis, surging by 21.6%. This segment is highly strategic, as it allows the company to push third-party or externally manufactured products, such as PVC pipes, through its existing logistics network, thereby increasing the drop size and profitability of each delivery truck without incurring additional fixed overhead.
The competitive positioning of the company is fortified by its strict adherence to quality and environmental standards. As a manifestation of its commitment to environmental management, occupational health and safety, and good corporate governance, the company has successfully obtained and implemented ISO 9001:2015 for its Quality Management System and ISO 14001:2015 for its Environmental Management System. These certifications are increasingly important for securing large-scale commercial contracts and maintaining brand prestige in a market where consumers are becoming more environmentally conscious.
Balance Sheet Architecture and Asset Quality
The statement of financial position reveals an enterprise characterized by extreme liquidity, zero structural leverage, and highly efficient working capital management.
| Balance Sheet Category | Mar 31, 2026 (IDR Millions) | Dec 31, 2025 (IDR Millions) |
|---|---|---|
| Current Assets | 8,283,910 | 7,821,844 |
| – Cash and Cash Equivalents | 2,214,410 | 1,654,810 |
| – Short-Term Investments | 2,424,261 | 2,570,080 |
| – Trade Receivables | 1,756,843 | 1,630,263 |
| – Inventories | 1,713,373 | 1,679,578 |
| Non-Current Assets | 3,328,517 | 3,262,535 |
| – Fixed Assets | 2,310,212 | 2,255,297 |
| Total Assets | 11,612,427 | 11,084,379 |
The most striking feature of the balance sheet is the immense concentration of liquid assets. As of March 31, 2026, the company held Rp 2.21 trillion in cash and cash equivalents, alongside an additional Rp 2.42 trillion in short-term investments. Combined, this Rp 4.63 trillion liquidity pool represents approximately 40% of the total asset base.
The cash and cash equivalents are predominantly held in Rupiah-denominated time deposits across various top-tier Indonesian banking institutions. The company maintains significant deposit balances with PT Bank Tabungan Negara Tbk ($BBTN) (Rp 550 billion), PT Bank Rakyat Indonesia Tbk ($BBRI) (Rp 400 billion), and PT Bank Mandiri Taspen (Rp 320 billion), yielding annual interest rates between 4.50% and 5.50%. Cash in current accounts is also distributed across reliable institutions like PT Bank UOB Indonesia and PT Bank Mandiri (Persero) Tbk ($BMRI) to facilitate daily operations.
The short-term investment portfolio is almost entirely composed of Indonesian Government Bonds, specifically Surat Utang Negara, valued at Rp 2.37 trillion. These government bonds bear fixed coupon rates ranging from 5.13% to 7.00% per annum and will mature on various dates extending to April 2032. The company also holds a minor allocation of Rp 52.3 billion in mutual funds. The government bonds are classified as financial assets measured at fair value through other comprehensive income. As of the end of the first quarter, the company recognized an unrealized mark-to-market loss of Rp 24.1 billion on these instruments, reflecting fluctuations in the prevailing interest rate environment.
While this massive liquidity buffer eliminates any near-term solvency risks and generated meaningful finance income of Rp 49.9 billion during the quarter, it also points to an inefficient capital structure. The blended yield on these cash reserves and government bonds is materially lower than the core operational return on invested capital. From an institutional investment perspective, holding 40% of the asset base in low-yielding government securities depresses the overall return on equity and suggests that cash is generated much faster than it can logically be deployed into core operations.
The company demonstrates strong control over its working capital cycle. Trade receivables stood at Rp 1.75 trillion, primarily denominated in Rupiah. An analysis of the aging schedule reveals high credit quality.
| Trade Receivables Aging | Mar 31, 2026 (IDR Millions) | Dec 31, 2025 (IDR Millions) |
|---|---|---|
| Not yet due | 1,699,516 | 1,590,071 |
| Overdue: 1-30 days | 43,969 | 20,294 |
| Overdue: 31-60 days | 10,031 | 10,316 |
| Overdue: Over 60 days | 6,187 | 12,442 |
| Less: ECL Allowance | (2,860) | (2,860) |
| Total Net Receivables | 1,756,843 | 1,630,263 |
The vast majority of the receivables, totaling Rp 1.69 trillion, are not yet due, consistent with the average credit period of 42 days. The simplified approach under PSAK 109 is employed to measure expected credit losses using a provision matrix based on historical default rates adjusted for forward-looking economic conditions. The accumulated expected credit loss allowance is a mere Rp 2.86 billion, representing a fraction of a percent of gross receivables. This highlights exceptional collection efficiency and a low-risk customer base.
Inventories increased slightly to Rp 1.71 trillion. The inventory mix is healthy, composed largely of finished goods valued at Rp 1.05 trillion and raw materials valued at Rp 309.4 billion. The provision for obsolescence and slow-moving inventory is conservatively maintained at Rp 26.2 billion, following an additional provision of Rp 2.5 billion recognized during the period. The slight build-up in in-transit inventory, which rose to Rp 149.5 billion, along with steady raw material levels, suggests a strategic decision to secure supply chain inputs ahead of anticipated cost inflations linked to the volatile crude oil market.
Non-current assets totaled Rp 3.32 trillion, anchored by fixed assets valued at Rp 2.31 trillion. Land is measured using the revaluation model under PSAK 216, utilizing independent appraisers and a market approach (Level 2 fair value hierarchy) that considers the price per square meter of comparable properties. The carrying value of land stands at Rp 561.2 billion. Investment properties, valued at Rp 289.8 billion, consist of land in Makassar and an office building in Surabaya. The building is valued using an income approach (Level 3 fair value hierarchy) incorporating an estimated rental rate of Rp 2.2 million per square meter and a discount rate of 9.67%.
The company also holds long-term investments totaling Rp 372.3 billion. This includes a strategic equity investment of Rp 290.8 billion in PT Dextone Lemindo, an adhesive manufacturer, representing a 16.67% ownership stake acquired in 2025. This investment is classified at fair value through other comprehensive income using Level 3 unobservable inputs. Additionally, long-term debt securities issued by PT Danantara Investment Management are held with a carrying value of Rp 81.5 billion, yielding 2% annually and maturing in 2030 and 2032. The 50% interest in a joint venture, PT Bangun Bersama Solusindo, is accounted for using the equity method. The carrying amount of this investment is Rp 20.9 billion, and the joint venture generated revenues of Rp 9.0 billion and a net profit of Rp 716 million during the first quarter.
Liability Structure and Capital Allocation
The liability side of the balance sheet is devoid of structural risk, reflecting a highly conservative approach to financial leverage.
| Liability Category | Mar 31, 2026 (IDR Millions) | Dec 31, 2025 (IDR Millions) |
|---|---|---|
| Current Liabilities | 1,608,142 | 1,457,408 |
| – Trade Payables | 785,949 | 784,207 |
| – Accrued Expenses | 411,144 | 293,400 |
| – Taxes Payable | 236,045 | 130,885 |
| – Short-Term Employee Benefits | 108,004 | 115,086 |
| Non-Current Liabilities | 89,320 | 86,747 |
| – Long-Term Lease Liabilities | 13,354 | 14,622 |
| – Employee Benefits Liability | 75,966 | 72,125 |
| Total Liabilities | 1,697,462 | 1,544,155 |
The company holds zero long-term interest-bearing bank debt. Short-term bank loans are practically non-existent at Rp 7.1 billion, primarily representing minor trade financing or overdraft facilities utilized by subsidiaries like PT Multipro Paint Indonesia. Massive untapped credit facilities are available, including a Rp 940 billion working capital line and a US$10 million treasury line from $BMRI, ensuring infinite operational liquidity.
Trade payables remained flat at Rp 785.9 billion. The 30 to 60-day credit terms are effectively utilized with suppliers to fund a significant portion of inventory requirements without incurring interest costs. A portion of these payables is denominated in foreign currencies, including Chinese Yuan and US Dollars, reflecting the global nature of raw material procurement. Accrued expenses rose substantially to Rp 411.1 billion, driven heavily by marketing and promotional accruals (Rp 296.2 billion), which include liabilities for customer loyalty programs.
The non-current liabilities of Rp 89.3 billion consist almost entirely of long-term lease liabilities and employee benefit obligations. Lease liabilities are accounted for under PSAK 116, measuring the present value of future lease payments discounted at the incremental borrowing rate. The employee benefit liability is calculated using the Projected Unit Credit method under PSAK 219. The independent actuarial valuation incorporates conservative assumptions, including a discount rate of 6.25% to 6.75%, an annual salary growth rate of 5% to 7%, and mortality rates based on TMI-IV-2019. The total employee benefit obligation stands at Rp 183.9 billion, with the non-current portion representing Rp 75.9 billion.
Given this debt-free status, the company operates with a purely equity-funded capital structure. Total equity reached Rp 9.91 trillion. The equity base is anchored by share capital of Rp 619.5 billion and additional paid-in capital of Rp 7.79 trillion, stemming from the initial public offering. To optimize this capital structure, management has aggressively engaged in capital return programs. During the first quarter of 2026, share buybacks totaling Rp 85.7 billion were executed, acquiring 187.2 million shares at prices ranging from Rp 380 to Rp 525 per share. This follows a massive buyback campaign in 2025 where Rp 645.3 billion was spent to acquire 1.47 billion shares. The total accumulated treasury shares amount to Rp 1.30 trillion, representing approximately 4.57% of the total issued shares. This aggressive buyback program, alongside substantial cash dividends, illustrates management’s awareness of its overcapitalized balance sheet and a commitment to returning excess liquidity to shareholders, thereby artificially supporting the earnings per share growth trajectory.
Cash Flow Economics and Scalability
The consolidated statement of cash flows provides compelling evidence of the status as a high-quality cash compounder.
| Cash Flow Summary | Q1 2026 (IDR Millions) | Q1 2025 (IDR Millions) |
|---|---|---|
| Cash Receipts from Customers | 2,207,396 | 1,992,736 |
| Payments to Suppliers | (1,203,049) | (1,341,780) |
| Payments to Employees | (246,090) | (223,472) |
| Cash Provided by Operations | 758,257 | 427,484 |
| Finance Income Received | 48,934 | 68,497 |
| Corporate Income Tax Paid | (97,631) | (50,384) |
| Net Cash from Operating Activities | 719,818 | 446,901 |
| Net Cash Used in Investing Activities | (545) | (526,514) |
| Net Cash Used in Financing Activities | (152,486) | (173,167) |
| Net Increase in Cash | 566,787 | (252,780) |
In the first quarter of 2026, the company generated Rp 719.8 billion in net cash from operating activities, representing a massive 61% increase from the Rp 446.9 billion generated in the corresponding period of 2025. Crucially, the operating cash flow significantly exceeded the reported net profit of Rp 502.7 billion. This cash conversion ratio of over 140% is a hallmark of a highly efficient business model. It proves that the reported earnings are not tied up in bloated receivables or unmanageable inventory accumulation. Instead, profits are immediately converted into tangible liquidity. The sharp decrease in payments to suppliers compared to the previous year (Rp 1.20 trillion versus Rp 1.34 trillion) despite higher sales volumes underscores exceptional working capital management and advantageous supplier negotiations.
Cash used in investing activities was practically flat at a net outflow of Rp 545 million. However, this net figure masks underlying strategic movements. The company received Rp 100 billion from maturing short-term investments while concurrently deploying Rp 87.9 billion toward the purchase of fixed assets.
This capital expenditure is highly strategic. A third manufacturing facility located in Cirebon is actively under construction. This new plant, scheduled for commissioning in the second quarter of 2026, will add an installed capacity of approximately 200,000 metric tons per year based on two working shifts. The total capital expenditure budget for this specific project is IDR 750 billion, of which 66% has already been deployed. Furthermore, existing capital expenditure commitments of Rp 367.8 billion not yet recognized as liabilities remain active.
The construction of the Cirebon facility highlights the scalability of the business. Because this massive infrastructure expansion is funded entirely from internal cash flows without requiring external debt or equity dilution, the incremental capacity will directly enhance future free cash flow generation. The Cirebon location strategically optimizes distribution logistics for the western regions of Java, which is expected to reduce future freight out expenses and improve the operational margin profile over the long term.
Net cash used in financing activities totaled Rp 152.4 billion, dominated by the outflow of Rp 85.7 billion for the acquisition of treasury shares and Rp 59.0 billion for the payment of lease liabilities. Under Indonesian accounting standards, the principal portion of lease payments is classified as a financing activity. The aggressive execution of the share buyback program underscores a financing strategy focused almost entirely on equity yield enhancement rather than debt servicing.
Dependency Risks, Corporate Governance, and Vulnerabilities
While the enterprise is fundamentally strong, specific dependency risks inherent in the operational architecture require rigorous scrutiny. The most pronounced vulnerability is the reliance on related party transactions, specifically concerning raw material procurement and supply chain integration.
| Related Party Transactions (Q1 2026) | Amount (IDR Millions) | % of Total Category |
|---|---|---|
| Purchases of Inventories | ||
| – PT Avia Avian Industri Pipa | 244,180 | |
| – PT Mitra Mulia Makmur | 105,670 | |
| – PT Wahana Lentera Raya | 61,969 | |
| – PT Kencana Lintasindo Internasional | 54,344 | |
| – Others | 17,940 | |
| Total Related Party Purchases | 484,103 | 37.29% of COGS |
| Trade Payables to Related Parties | 327,745 | 19.31% of Liabilities |
The financial statements identify several related entities under common control by key management personnel, including PT Avia Avian Industri Pipa, PT Mitra Mulia Makmur, PT Wahana Lentera Raya, and PT Kencana Lintasindo Internasional. An analysis of the purchasing dynamics exposes a massive concentration. In the first quarter of 2026, inventory totaling Rp 244.1 billion was purchased from PT Avia Avian Industri Pipa alone. Total purchases from all related parties aggregated to Rp 484.1 billion for the quarter. To contextualize this magnitude, related party purchases account for an astonishing 37.29% of the total consolidated cost of goods sold. Correspondingly, trade payables to related parties stand at Rp 327.7 billion, representing 19.31% of total consolidated liabilities.
This high degree of related-party supply chain integration introduces material corporate governance and transfer pricing risks. While explicitly stating these transactions are conducted on mutually agreed terms in the normal course of business, institutional investors generally apply a risk discount when over a third of a company’s raw materials and trading goods are sourced from private entities controlled by the same ultimate beneficial owners. If the pricing dynamics between these private entities and the public company shift unfavorably, it could lead to sudden margin deterioration that minority public shareholders cannot predict or easily contest.
Beyond related-party risks, traditional financial vulnerabilities are actively managed. The foreign exchange risk is monitored closely, as net monetary liabilities in foreign currencies equivalent to Rp 134.7 billion are held, primarily stemming from US Dollar and Chinese Yuan trade payables. A sensitivity analysis indicates that a 10% depreciation of the Rupiah against the US Dollar would decrease net profit by Rp 4.9 billion. Furthermore, the company is exposed to price risk on its massive portfolio of government bonds and mutual funds. A 5% movement in the required market yield would result in a Rp 121.2 billion fluctuation in comprehensive income, highlighting the sensitivity of the overcapitalized balance sheet to macroeconomic interest rate cycles.
Valuation Framework and Implied Attractiveness
Evaluating the true investment merit of the enterprise requires a distinct valuation framework. As of late April 2026, the company’s shares are trading in the vicinity of IDR 370 to 390 per share on the Indonesia Stock Exchange. Following the aggressive share repurchases, there are approximately 59.1 billion shares outstanding (excluding the 2.8 billion treasury shares). This implies a market capitalization of approximately IDR 22.4 trillion.
The net profit generated in the first quarter of 2026 was Rp 503.1 billion, which translates to a basic earnings per share of Rp 8.50. Annualizing this performance yields an estimated forward earnings per share of approximately Rp 34. At a current share price of IDR 380, the business is trading at a forward Price-to-Earnings multiple of approximately 11.1x.
This multiple presents a highly compelling valuation discrepancy. A business exhibiting these characteristics—an undisputed market leader, possessing pricing power capable of offsetting global commodity shocks, generating a return on invested capital vastly superior to its cost of equity, and operating with a flawless, debt-free balance sheet holding 40% of its assets in pure cash and equivalents—traditionally commands a premium valuation in public equity markets, often trading at multiples in the 18x to 25x range globally.
The current discounted valuation of approximately 11x earnings can likely be attributed to a confluence of specific factors. Firstly, the broader Indonesian equity market may be applying a macro-discount due to the depreciating Rupiah and foreign capital outflows typical of periods characterized by geopolitical stress. Secondly, the extreme related-party procurement concentration introduces a persistent governance overhang that deters strict institutional mandates. Finally, the overcapitalized balance sheet actively suppresses the aggregate return on equity. The Rp 4.6 trillion sitting in cash and government bonds earns a nominal yield, dragging down the consolidated returns of the enterprise.
However, management is actively and aggressively addressing these capital structure inefficiencies. The share buyback program, acquiring shares at these depressed multiples, is highly accretive to intrinsic value per share. Furthermore, the massive dividend payouts demonstrate an absolute commitment to shareholder yield. Following the 2025 financial year, a total cash dividend of IDR 1.36 trillion was authorized, equivalent to IDR 23 per share, representing a stellar payout ratio of 78.18%. This included an interim dividend of IDR 11 per share paid in November 2025 and a final dividend of IDR 11 per share paid in April 2026. For a value-oriented investor, purchasing a dominant consumer monopoly at 11x earnings, backed by a massive cash hoard and a management team actively returning capital, presents a deeply asymmetric risk-reward profile skewed heavily to the upside.
Rp 336
MCap: 20.82 T
Strategic Investment Implications
The financial evidence unambiguously points to a structurally elite enterprise. PT Avia Avian Tbk represents a high-conviction investment opportunity that fundamentally justifies a premium valuation framework, despite currently trading at a significant market discount.
The 16.8% top-line revenue growth and 12.6% net profit expansion during a period of demonstrably sluggish domestic housing data prove the recession-resistant nature of its renovation-driven revenue model. The ability to maintain a gross margin near 45% while navigating a severe global supply chain shock—driven by a massive surge in crude oil prices—validates the existence of a wide economic moat and absolute pricing power.
Earnings quality is pristine, validated by operating cash flows that exceed reported net income by over 140%, eliminating concerns of artificial accounting accruals. The balance sheet is impregnable, characterized by zero structural bank debt and immense, highly liquid reserves. The company funds its major capacity expansions, such as the Cirebon facility, entirely through internal free cash flow, guaranteeing future scale without shareholder dilution.
While the heavy reliance on related-party suppliers for over a third of raw material procurement introduces a permanent governance monitoring requirement, the financial output suggests these relationships have not been detrimental to public shareholder profitability to date. Management’s highly disciplined capital allocation—executing aggressive share repurchases and distributing outsized dividends exceeding a 78% payout ratio—signals a profound alignment with minority shareholder interests. At current implied market multiples, the equity does not reflect the underlying durability, structural profitability, or cash-generating capacity of the business. Consequently, the enterprise is not merely a cyclical construction materials play; it is a high-quality, durable compounder trading at a severe dislocation to its intrinsic economic value.
Disclaimer
aluna Analytics is an independent research collective that operates without affiliation to any financial institution, broker, or advisory firm. We do not hold licenses as a securities dealer, investment advisor, or portfolio manager.
All materials published by aluna Analytics are created solely for informational and educational purposes. They reflect independent analytical interpretation and should not be regarded as personalized investment advice, solicitation, or endorsement of any security or strategy.
Market data, opinions, and projections presented herein are subject to change and may not predict future results. Readers remain fully responsible for any financial decisions made based on the information provided. We strongly encourage conducting personal due diligence and consulting a licensed professional before making investment commitments.
aluna Analytics is not regulated by the Financial Services Authority of Indonesia (OJK) and does not offer investment management or brokerage services. All content is presented in good faith, aiming to foster research literacy and informed market perspectives.